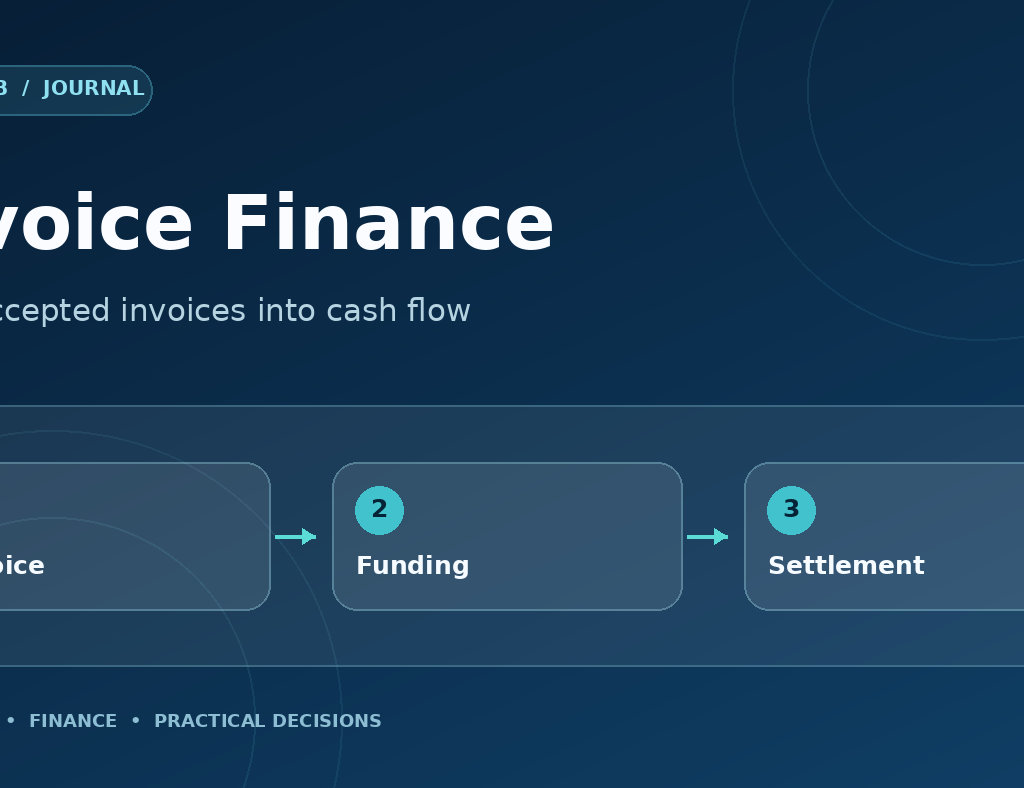
A wholesaler may have delivered goods and issued an invoice while the buyer’s payment is still weeks away. Invoice financing can bridge part of that timing gap when an eligible lender offers it.
1 · Check the inputs2 · Compare terms3 · Keep evidence
Trace the invoice-to-cash path
- Create a valid invoice backed by delivery and acceptance evidence. Disputed or cancelled invoices may not qualify.
- Ask who provides financing, the advance percentage, charges and whether the facility has recourse to the seller.
- Confirm how the buyer will be notified, where payment must go and how collections will be allocated.
- Reconcile financing proceeds, lender charges and final buyer payment against the original invoice.
A practical example
If a buyer owes ₹2,00,000 in 30 days, a financing offer may advance part of the invoice value now. The remaining amount, less disclosed costs, is settled later under the lender’s contract.
Before you act
Invoice financing is not automatic or free. Credit approval and pricing belong to the lender; compare them with the cost of waiting for payment.
Official or primary reference: RBI FAQs. Check the latest terms at source before making a financial decision.
Keep supplier orders and invoices organised in your Rawhub dashboard.